Property Tax in Pakistan 2026 With Real Cost Examples
A filer buying a PKR 3 crore property can face PKR 27.75 lakh less in advance tax than a non-ATL buyer under the current federal rate card. That difference can change the property, location or plot size you can afford. Yet buyers often calculate only the seller's demand and discover the tax bill near transfer day. This guide explains property tax in Pakistan 2026 through practical examples at PKR 50 lakh, PKR 1 crore and PKR 3 crore. It focuses on federal advance income tax collected from buyers and sellers during property transfers. Annual provincial property tax, stamp duty, registration, authority fees and dealer commission are separate costs.
Who Should Read This Tax Guide?
This guide is useful for anyone planning to buy or sell property in Pakistan during Tax Year 2027. It is especially important for first-time buyers, non-ATL investors and families working with a fixed budget. Overseas Pakistanis should also understand the figures before transferring money. Qualifying non-residents may qualify for special filer-rate treatment, but it requires the prescribed documents and approval process. Every buyer should confirm their tax position before paying non-refundable token money.
Property Tax in Pakistan 2026 at a Glance
The Finance Act 2026 changed the federal advance tax collected on the purchase or sale of immovable property. FBR's Tax Year 2027 withholding rate card is updated through 30 June 2026 and provides the current published rates. The underlying law prevails if any conflict appears in the rate card.
Buyer tax under Section 236K
Section 236K applies when a person purchases immovable property. FBR's current rate card lists a flat 1.25% rate for buyers appearing on the Active Taxpayers List. For non-ATL buyers, the published rate depends on fair market value:
Up to PKR 5 crore: 10.5%
Above PKR 5 crore and up to PKR 10 crore: 14.5%
Above PKR 10 crore: 18.5%
These percentages apply to the fair market value used for tax purposes. Do not apply them casually to an online advertisement or an unverified dealer quotation.
Seller tax under Section 236C
Section 236C applies when immovable property is sold or transferred. FBR's current rate card lists 2.75% for sellers appearing on the ATL and 11.5% for non-ATL sellers. The seller-side rate is calculated on the gross consideration received. The current rate card shows the same percentage within each published value band, but the actual amount increases with the transaction value.
These are not the only transaction costs
Sections 236K and 236C concern federal advance income tax. Buyers and sellers may also face provincial duties, registration expenses, housing-authority charges, membership fees, commission and outstanding property dues. A complete cost sheet must show each charge separately. Describing one percentage as the "total property tax" can leave a buyer seriously underfunded at transfer.
Buyer Tax Examples at Three Property Values
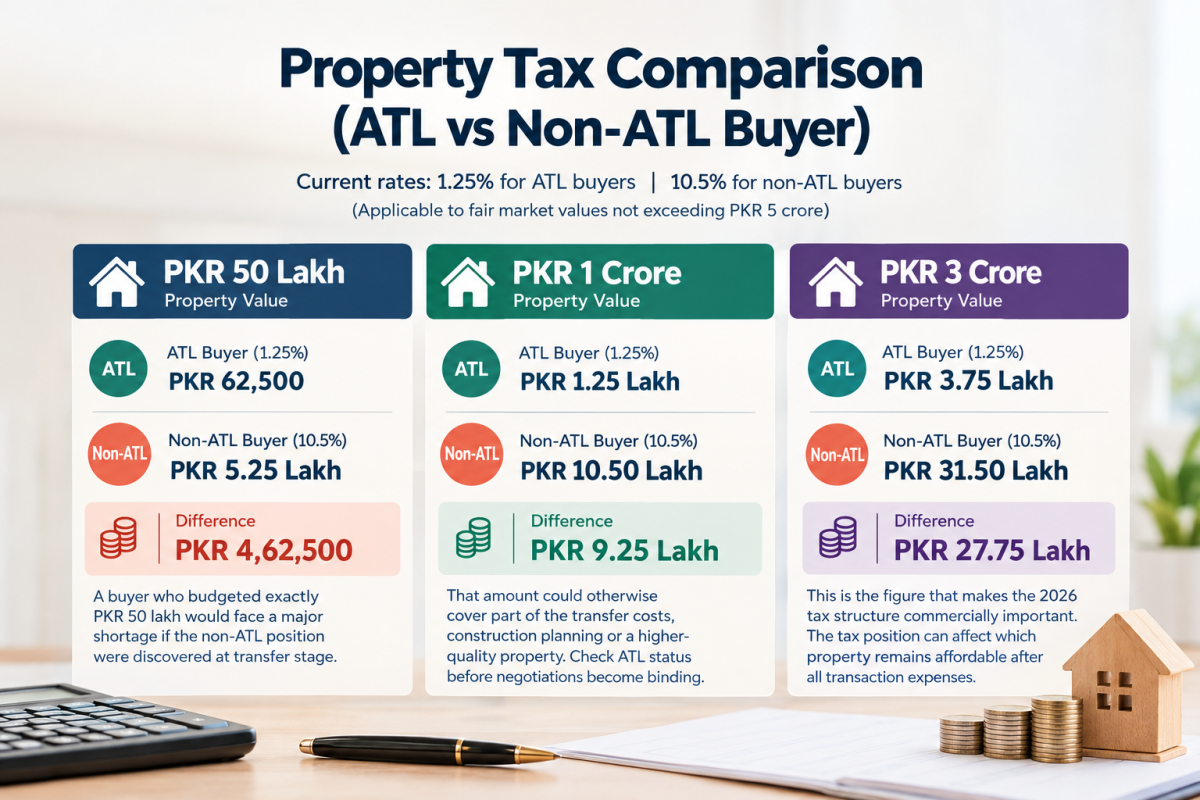
The following calculations use the current 1.25% ATL buyer rate and the 10.5% non-ATL rate applicable to fair market values not exceeding PKR 5 crore. They are illustrations based on the stated values, not personalized tax assessments.
Buying a PKR 50 lakh property
For an ATL buyer, 1.25% of PKR 50 lakh equals PKR 62,500. For a non-ATL buyer, 10.5% equals PKR 5.25 lakh. The difference is PKR 4,62,500. A buyer who budgeted exactly PKR 50 lakh would therefore face a major shortage if the non-ATL position were discovered at the transfer stage.
Buying a PKR 1 crore property
For an ATL buyer, the calculated Section 236K amount is PKR 1.25 lakh. A non-ATL buyer at 10.5% would pay PKR 10.50 lakh. The difference is PKR 9.25 lakh. That amount could otherwise cover part of the transfer costs, construction planning or a higher-quality property. Check ATL status before negotiations become binding.
Buying a PKR 3 crore property
At PKR 3 crore, an ATL buyer's calculated advance tax is PKR 3.75 lakh. The non-ATL calculation reaches PKR 31.50 lakh. The difference is PKR 27.75 lakh. This is the figure that makes the 2026 tax structure commercially important. The tax position can affect which property remains affordable after all transaction expenses.
Seller Tax Examples Under Section 236C
Sellers also need a cash-flow estimate before accepting a buyer's offer. The amount collected at transfer affects the money immediately available after the transaction.
Selling for PKR 50 lakh
At the published 2.75% ATL rate, the seller-side calculation is PKR 1,37,500. At the 11.5% non-ATL rate, it becomes PKR 5.75 lakh. The difference is PKR 4,37,500. A seller who ignores this deduction may overestimate the money available for another purchase.
Selling for PKR 1 crore
An ATL seller would face an illustrative Section 236C collection of PKR 2.75 lakh. A non-ATL seller would face PKR 11.50 lakh. The difference is PKR 8.75 lakh. Commission, outstanding dues and other expenses would still need to be deducted before calculating the seller's usable proceeds.
Selling for PKR 3 crore
At PKR 3 crore, the ATL calculation is PKR 8.25 lakh. The non-ATL calculation reaches PKR 34.50 lakh. The difference is PKR 26.25 lakh. This does not determine the seller's final income-tax liability or capital gain on its own. It shows the advance amount collected at the transaction stage under the published rate.
Why Fair Market Value Matters
The tax calculation may use a prescribed fair market value rather than the number discussed informally between a dealer, buyer and seller. This is why two people quoting the same property can produce different tax estimates if they use different valuation assumptions. FBR issued SRO 876(I)/2026 concerning the valuation of immovable property in Lahore on 19 May 2026. Buyers in Lahore should therefore use the applicable current valuation rather than an old chart saved on a phone.
Market price and tax value are different concepts
The market price reflects what a seller demands and a buyer agrees to pay. The applicable tax value follows the valuation and legal rules used by the relevant authorities. Do not substitute one figure for the other without verification. Request a written calculation showing the property, valuation basis, tax section, applicable percentage and resulting amount.
Why ATL Status Should Be Checked Early
Appearing on the Active Taxpayers List can materially reduce withholding tax on property transactions. FBR specifically identifies a lower tax rate on buying and selling property as an ATL benefit. Check the buyer's and seller's status before token money becomes non-refundable. Do not assume that filing a return today will instantly produce the required status for tomorrow's transfer. Late-filer treatment, ATL updating and individual compliance can require professional confirmation.
The seller's status affects the negotiation
A seller expecting a large deduction may attempt to recover part of it through a higher asking price. That does not make the buyer legally responsible for the seller's tax. Both parties should understand their separate obligations. The agreement should state the property price and payment responsibilities without hiding tax adjustments inside an unexplained lump sum.
What Overseas Pakistanis Should Know
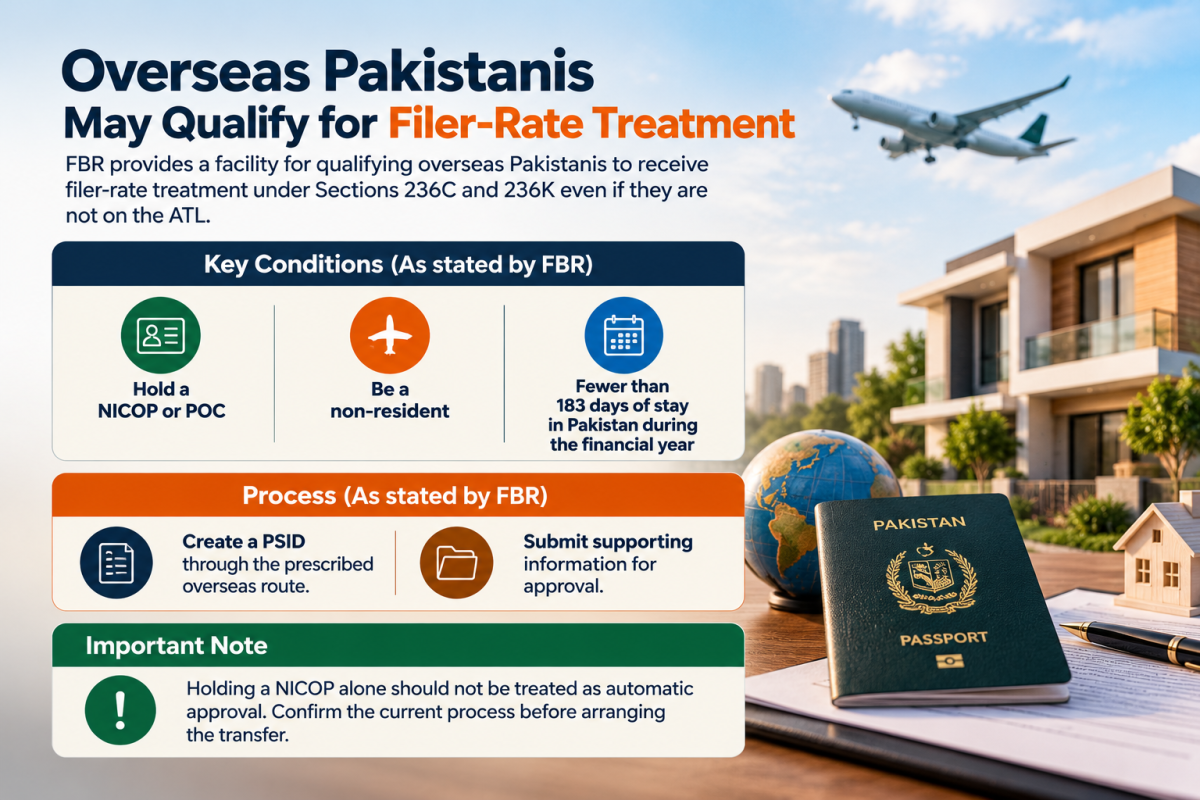
FBR publishes a facility through which qualifying overseas Pakistanis may receive filer-rate treatment under Sections 236C and 236K even when they are not on the ATL. Its stated conditions include holding a NICOP or POC and being a non-resident, with fewer than 183 days of stay in Pakistan during the financial year. The process involves creating a PSID through the prescribed overseas route and submitting supporting information for approval. Holding a NICOP alone should not be treated as automatic approval. Confirm the current process before arranging the transfer.
Build a Complete Property Cost Sheet
A strong buying decision combines taxes with every other amount needed to complete and hold the property. This prevents a low asking price from creating a false impression of affordability. Include:
Seller's agreed price
Section 236K buyer tax
Relevant provincial duties and registration costs
Housing-authority transfer and membership charges
Dealer commission
Verification and documentation expenses
Outstanding installments or dues
Estimated holding or construction costs
Currency and banking costs for overseas buyers
A reserve for verified but unsettled charges
Keep tax estimates separate from market assumptions. If you can't confirm a charge, label it clearly instead of presenting it as final.
Mistakes That Can Produce the Wrong Tax Estimate
Most tax errors begin with an incorrect value, outdated rate or misunderstood taxpayer status. A clean calculation is only useful when its inputs are correct. Avoid:
Using a pre-July 2026 rate sheet
Applying the ATL rate without checking status
Treating asking price as the automatic tax value
Calling Section 236K the complete transfer cost
Ignoring seller-side withholding
Assuming a NICOP creates automatic exemption
Treating advance tax as identical to final liability
Forgetting provincial and authority charges
Relying on screenshots without an official source
Paying token money before calculating the full budget
Tax rules and valuation schedules can change. Confirm the applicable position on the actual transfer date.
Conclusion
Understanding property tax in Pakistan 2026 can prevent a costly budget error. Under FBFBR'surrent Tax Year 2027 rate card, an ATL buyer is subject to a published 1.25% rate under Section 236K, while non-ATL buyer rates begin at 10.5%. Sellers face a published 2.75% ATL rate or 11.5% non-ATL rate under Section 236C. These are advance income-tax collections, not the complete cost of transferring property. Verify ATL status, fair market value and every additional charge before paying token money. Aslaaf Builders helps buyers compare property costs using current market information. Follow Aslaaf Builders on Facebook, LinkedIn and X for practical property updates.
FAQs about property tax in Pakistan 2026
Property buyers frequently confuse advance income tax, annual property tax and transfer charges. These answers address the main transaction questions, but a qualified professional should provide individual tax advice.
What is the buyer tax rate for a filer in 2026?
FBFBR's tax year 2027 rate card lists an ATL rate of 1.25% under Section 236K. The calculation is based on the applicable fair market value.
How much tax does a non-filer pay when buying property?
The current non-ATL rates under Section 236K are 10.5%, 14.5% or 18.5%, depending on the property's fair market value band.
Is Section 236K the total property transfer tax?
No. It is a federal advance income-tax collection from the purchaser. Provincial duties, registration, authority charges, commission and other expenses may also apply.
What is the seller tax rate under Section 236C?
FBFBR'surrent rate card lists 2.75% for ATL sellers and 11.5% for non-ATL sellers, calculated on gross consideration received.
Can an overseas Pakistani receive the filer rate?
A qualifying NICOP or POC holder may access filer-rate treatment through FBR's prescribed overseas process, subject to non-resident conditions, documentation, and approval.


0 Comments
syed ahmad
June 8, 2018 AT 07:05 PM
thank you for this advice